
How are NSW CTP claims made for injured children?
A child injured as a passenger, pedestrian, cyclist or in another NSW motor accident can potentially make a CTP personal injury claim. The child is the injured claimant, but a parent, guardian or other suitable adult will usually manage forms, treatment communication and evidence. If the matter goes to the Personal Injury Commission (PIC), a person under 18 is under legal incapacity for those proceedings and must act through an appointed representative.
Start the claim in the child’s name, obtain age-appropriate medical care and keep a careful record of school, sleep, behaviour, activity and treatment changes. Do not assume the child has no claim because a parent or family driver may have caused the crash. Statutory benefits and any later damages claim have separate tests.
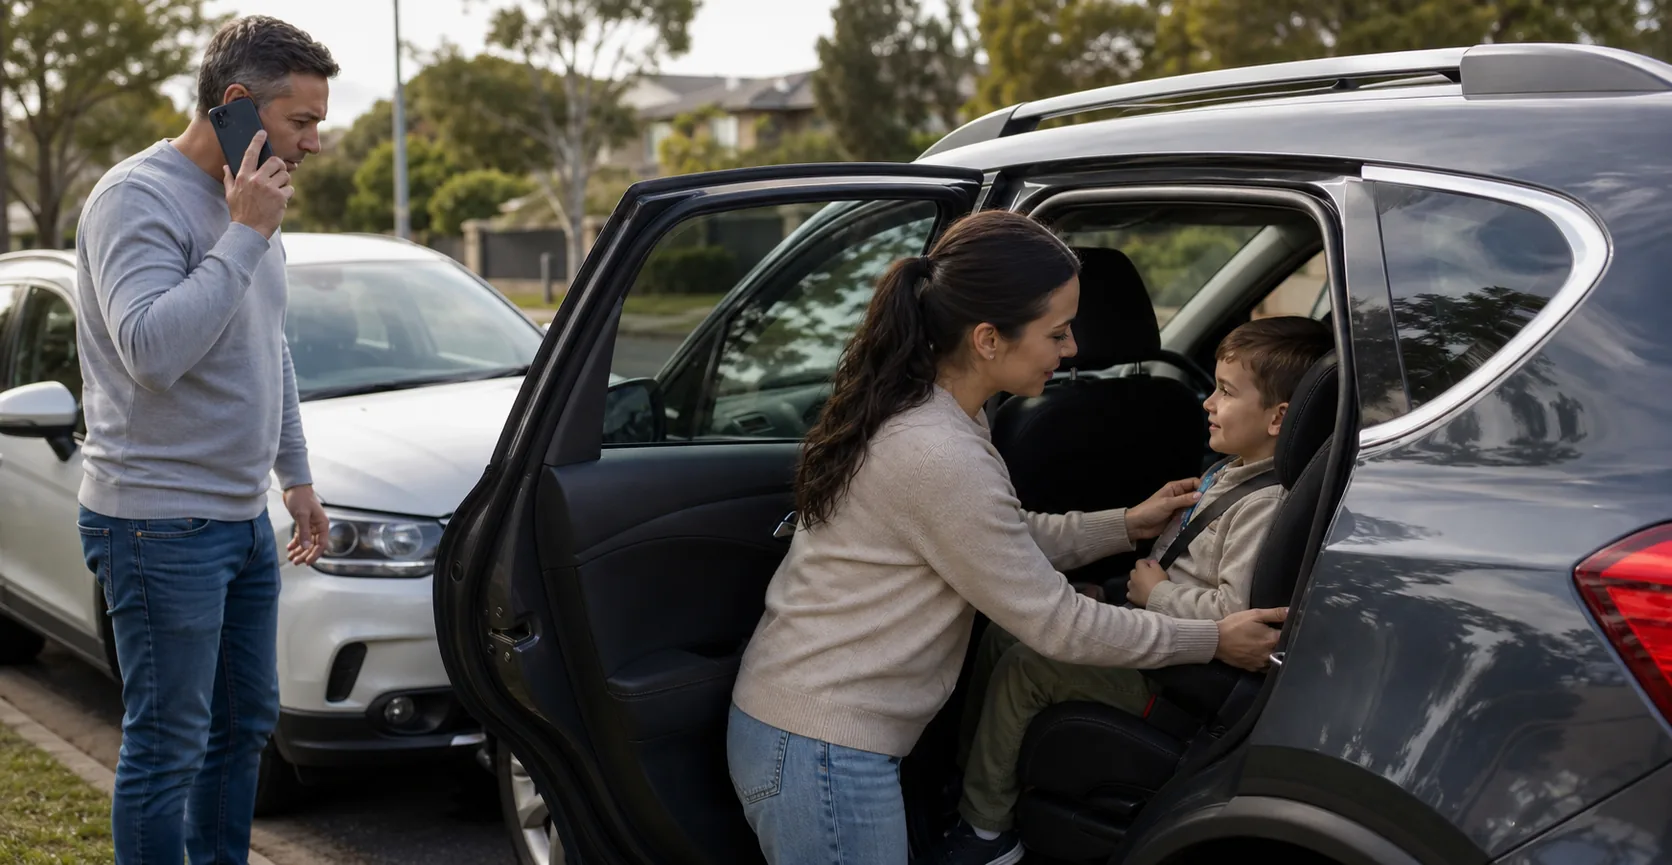
How this accident occurs
- A child is injured in a family car, taxi, rideshare, school-related trip or another vehicle.
- A child is struck as a pedestrian or cyclist, or is injured when a vehicle brakes or swerves.
- Symptoms may be immediate or appear through headaches, sleep change, anxiety, reduced play, school absence or developmental concerns.
Who may claim
The child is the claimant. A parent, guardian or other appropriate adult may assist with the insurer claim. Under section 7.47 of the Motor Accident Injuries Act 2017, a person under 18 is under legal incapacity for PIC proceedings and acts through an appointed representative. The representative must be suitable, willing and able to act and must not have an adverse interest. The role and any later settlement step should be checked for the particular stage rather than assumed from family status alone.
Realistic examples
- A rear-end crash causes neck pain and headaches that affect school attendance.
- A side impact causes an abdominal injury where the child restraint and seating position need investigation.
- A child develops a recognised psychological condition after a serious crash involving a family member.
Common injuries
- Head injury or concussion symptoms, fractures, abdominal or chest injury, and neck or back symptoms.
- Seatbelt or child-restraint bruising, limb injury and pain that limits play or school activity.
- Psychological injury supported by diagnosis, treatment history and functional change rather than distress alone.
Statutory benefits
A statutory benefits claim after child-passenger injury claims can seek treatment and care expenses and, where work capacity is affected, weekly payments. These benefits are decided under the NSW motor accident scheme and insurer decisions can be reviewed or disputed. Statutory benefits do not automatically mean a person also has a damages entitlement.
When common law damages may be possible
A common law damages claim after child-passenger injury claims is separate from statutory benefits. It may be possible only if the legal requirements are met, including fault, injury classification and other statutory thresholds. The accident type helps identify evidence, but it does not by itself create any entitlement to compensation or damages.
Accident-specific fault issues
- A child passenger may claim even if the driver of the child’s own vehicle was at fault.
- Restraint or seating allegations must be checked against the child’s age, the evidence and causation; they do not automatically end the claim.
- Statutory benefits do not automatically establish fault or a damages entitlement.
- Long-term impairment may need cautious assessment because a child is still growing and developing.
Evidence to preserve
- Claim form and insurer correspondence identifying the child and the adult assisting.
- Ambulance, hospital, GP, paediatric, psychology and rehabilitation records.
- School attendance, teacher observations, activity changes and a dated symptom history.
- Photos of the seating position, restraint and vehicle damage, plus police, witness and camera evidence.
What to do next
- 1
Obtain appropriate medical care and record all physical, emotional and behavioural changes.
- 2
Lodge the claim in the child’s name and identify the adult assisting with the form.
- 3
Preserve restraint, seating, vehicle, witness, police and camera evidence.
- 4
Keep school, care, treatment and out-of-pocket records in one dated chronology.
- 5
Get advice before accepting a restraint allegation, long-term impairment result or proposed settlement.
How can a NSW CTP claim be lodged?
A NSW CTP claim is not one single form for every entitlement. Statutory personal injury benefits, common law damages and death-related claims have different approved forms, evidence requirements and legal tests.
- Statutory personal injury benefits are claimed from the relevant CTP insurer using the current approved Application for Personal Injury Benefits or the NSW Government online claim process. A treating medical practitioner certificate and police event details should be provided where available.
- A common law damages claim is separate. It uses the current Application for Common Law Damages and depends on fault, injury classification and statutory requirements. Receiving statutory benefits does not automatically create a damages entitlement.
- A claim may be lodged directly with the insurer through accepted channels such as the NSW Government online claims system, an insurer online claim system, or the written approved form sent by email, personal delivery, facsimile or post where available.
- If a lawyer is instructed, the lawyer can help identify the insurer, prepare the approved forms, gather medical and accident evidence, and lodge the claim or dispute on the client's behalf.
- Where the registration number is known, insurer details can usually be checked through Service NSW registration information or SIRA CTP Assist. If the vehicle is uninsured or unidentified, the claim may need to proceed through the Nominal Defendant pathway.
- For a child or a person unable to make the declaration, the approved forms allow an appropriate parent, guardian, relative, friend or legal personal representative to assist or sign, with their relationship and reason for acting identified.
- If the accident occurred while working, a separate workers compensation claim may also be required and the CTP and workers compensation pathways should be coordinated.
- CTP covers personal injury or death arising from a motor accident. It does not cover ordinary vehicle repairs or property damage, which usually sit with property damage, comprehensive insurance or other recovery pathways.
Time limits, police reporting and late claims
The current NSW scheme has several different timing rules. The safest approach is to report the accident, obtain medical evidence and lodge the correct claim form as early as possible.
- Police reporting: the current SIRA personal injury benefits form says the accident must be reported to police within 28 days. A police event number should be provided, but the form also says a claim can still be submitted while that number is being obtained.
- Statutory benefits: a claim for statutory benefits is generally required within 3 months after the motor accident. A later claim needs a full and satisfactory explanation and must satisfy the Act's late-claim conditions.
- 28-day significance: if a statutory benefits claim is not made within 28 days, weekly payments are generally not backdated for the period before the claim is made unless the Regulation permits it.
- Accidents on or after 1 April 2023: backdated weekly payments may still be considered if the claim is made within 3 months and a full and satisfactory explanation is provided. The Regulation sets factors such as awareness of the right to claim, legal incapacity, illness or injury preventing earlier lodgement, and a 14-day deemed-acceptance rule if the insurer does not reject the explanation.
- Damages: a common law damages claim is generally required within 3 years after the motor accident. A late damages claim requires a full and satisfactory explanation and is assessed separately from any statutory benefits claim.
- Older scheme: accidents before 1 December 2017 were handled under the previous NSW motor accidents scheme and different forms/time limits, including older six-month claim concepts, may apply. This accident type cluster is written for the post-1 December 2017 scheme unless a page says otherwise.
- Review and dispute deadlines can be shorter and decision-specific. Internal review, medical assessment, merit review and PIC steps should be checked as soon as an insurer decision is received.
Common insurer disputes
- The insurer says symptoms are unrelated, short-lived or not supported by age-appropriate clinical evidence.
- Treatment, psychology, travel, care or rehabilitation is said not to be reasonable and necessary.
- The insurer relies on a restraint issue without proving how it caused or increased the particular injury.
- A WPI or damages decision is premature because the child’s condition has not stabilised or development remains relevant.
FAQs
Is the parent or the child the claimant?
The injured child is the claimant. A parent, guardian or other suitable adult may manage insurer steps, while PIC proceedings require an appointed representative for a person under 18.
Can a child claim if their own parent caused the crash?
Potentially, yes. A passenger claim is not automatically excluded because the driver was a parent or family member. Fault, insurer identity, causation and the separate damages rules still require evidence.
Do children receive weekly payments?
Weekly payments are income-replacement benefits and depend on the statutory earner and loss requirements. Treatment and care questions are separate and may arise even where the child had no earnings.
When is a child’s permanent impairment assessed?
Only when the assessment is medically appropriate. The Motor Accident Guidelines recognise that assessment may need to wait where growth or development could materially affect the outcome.
Can an insurer reject a child’s claim because the child restraint was wrong?
Not automatically. The insurer must address the evidence, the applicable restraint requirements, causation and any contributory-negligence issue. The child may still have a claim.